What does fuel margin actually measure?
Fuel margin measures the spread between fuel selling revenue and a clearly defined cost base. It is useful only when everyone knows which deductions are included. A petrol station margin report that excludes card fees cannot be compared directly with a gas station profit margin report that includes them. Start by agreeing the definition, the measurement period and the treatment of taxes before discussing whether performance is good or bad.
Use three separate measures: gross fuel spread, retained fuel contribution and site operating profit. Gross spread compares selling revenue with fuel acquisition cost on a consistent tax basis. Retained contribution subtracts direct selling deductions such as card fees and measured stock loss. Site operating profit then reflects labour, rent, utilities, maintenance and other operating expenses. Naming these layers prevents an attractive pump spread from disguising weak economics across the forecourt.
How do you calculate fuel margin per litre?
Calculate revenue and cost over matching sales volumes. Use actual realised selling prices after discounts, not the headline price displayed on the board. Build acquisition cost from the applicable supply invoice, delivery charges and contractual adjustments. Where recoverable taxes are excluded from revenue, exclude them consistently from costs. Nonrecoverable duties require explicit treatment; tax rules depend on the jurisdiction and should be checked with the responsible finance adviser.
Use a consistent tax basis and avoid deducting freight or stock losses twice if already included in acquisition cost.
For example, suppose tax-consistent fuel revenue is $150,000 and matched acquisition cost is $137,000 on 100,000 litres. Gross fuel margin is $0.13 per litre. If direct selling deductions total $3,000, retained contribution is $0.10 per litre, or $10,000 for the period. These illustrative figures describe contribution before site overhead, financing and income tax; they do not establish a target for another station.
Which acquisition cost should you use?
For accounting performance, use the inventory valuation method agreed with finance and match the cost of stock sold to the period. For a pricing decision, also examine replacement cost: the expected cost of replenishing the next delivery. Keep both views labelled. A falling replacement price can make a current pump price look comfortable even while older, more expensive tank stock is being sold at a disappointing realised margin.
What does a rack-to-retail margin bridge show?
A margin bridge makes the price stack visible. The following illustrative bridge starts with rack cost, adds freight, duties, card fees and wetstock loss, and finishes with retained contribution inside the retail price. Here, net margin means retained contribution before site overhead. It is not net business profit. Actual card charges may apply to the full transaction value, so calculate the fee from the settlement terms rather than assuming a fixed deduction.
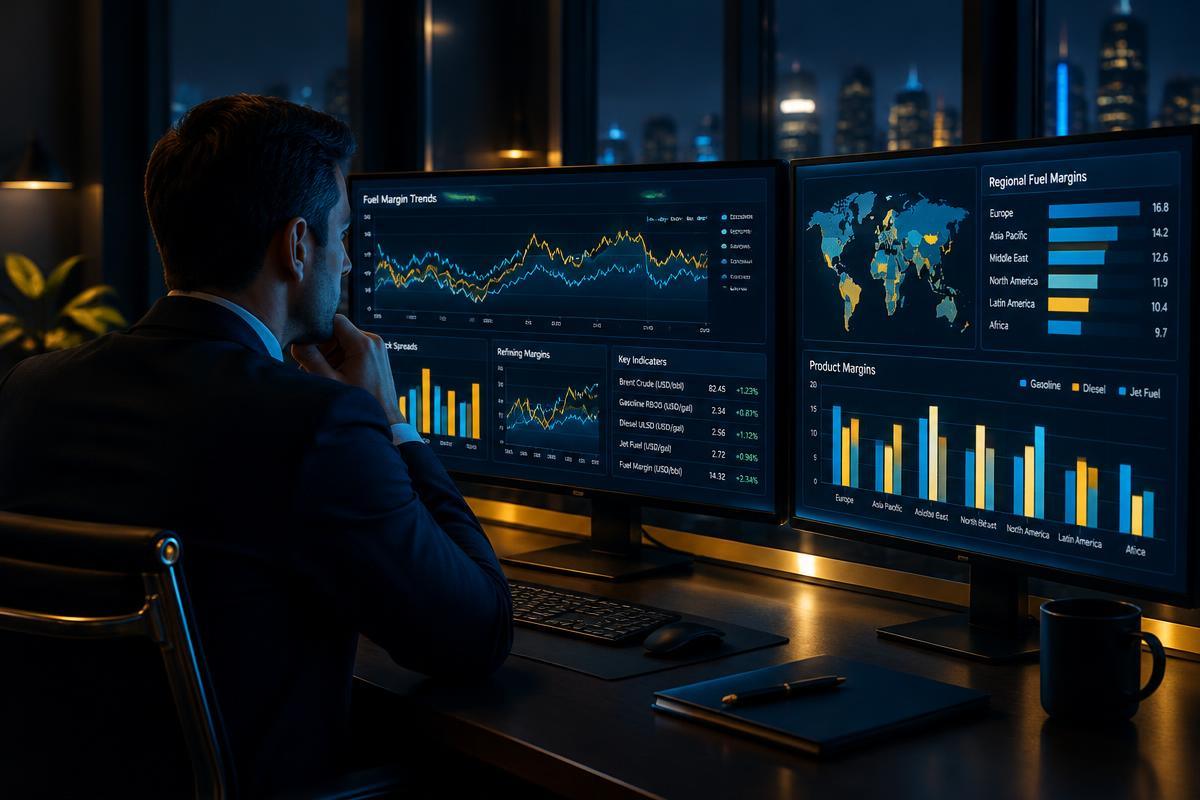
Use the bridge to locate the movement, not just display the result. If retained contribution falls while retail price rises, the cause may be a larger wholesale increase, a changing payment mix or stock loss. Assign each component to a source document and an owner. A bridge that cannot be tied back to supplier invoices, point-of-sale totals, settlement records and stock reconciliation is a presentation, not a reliable control.
How do you convert margin into cents per gallon?
Convert the volume unit without changing the underlying economics. One US gallon contains approximately 3.785 litres; an imperial gallon contains approximately 4.546 litres. Multiply cents per litre by the relevant conversion factor to obtain cents per gallon. Divide in the opposite direction. Always state the gallon convention, currency and tax basis because an unlabelled cents per gallon comparison can mislead operators working across different markets.
| Measure | Illustrative calculation | Result |
|---|---|---|
| Cents per litre | 10.00 cents per litre | 10.00 ¢/L |
| Cents per US gallon | 10.00 × 3.78541 | 37.85 ¢/US gal |
| Cents per imperial gallon | 10.00 × 4.54609 | 45.46 ¢/imperial gal |
Do not confuse a margin amount with a margin percentage or markup. Margin percentage divides contribution by sales revenue, while markup divides the spread by cost. For example, a $0.10 contribution on a $1.50 selling price is approximately 6.67% of revenue. That illustrative percentage is different from adding 10% to acquisition cost. Specify both the numerator and denominator whenever a report uses percentages.
How can a fuel station improve retained margin?
Change pricing with contribution in view
Set a price-review routine that considers replacement cost, local competitors, demand patterns and supply restrictions together. Avoid mechanically matching every competitor move. Track litres, realised contribution and customer response after each decision. A lower price is worthwhile only when the additional contribution from incremental sales and associated store purchases exceeds the contribution surrendered on existing sales, after allowing for the extra operating burden.
For example, cutting price by one cent across an illustrative existing volume of 20,000 litres sacrifices $200 before any change in demand. If incremental litres retain eight cents each after the cut, 2,500 additional litres are needed just to replace that contribution, before additional operating costs. This is a decision framework, not a demand forecast. Test assumptions against observed transactions rather than treating hoped-for volume as earned income.
Control deductions before changing the board
Check freight billing, delivery minimums, payment rates, loyalty deductions and invoice adjustments against agreements. Reconcile wetstock before treating unexplained loss as normal. Separate discount-led sales from full-price transactions so blended averages do not hide leakage. Andrils Daily combines margin per litre, competitor pricing and daily reconciliation so the operator can review the commercial decision alongside the evidence supporting it.
Which daily controls make margin reports trustworthy?
Close the reporting day consistently across point-of-sale, tank, delivery and card-settlement systems. Record deliveries spanning the cutoff and isolate missing transactions rather than forcing the accounts to balance. Keep an exceptions log showing the cause, estimated contribution effect, responsible person and resolution date. Correct source data with an audit trail; unexplained manual adjustments can make a daily chart look stable while weakening the monthly accounts.
Review by grade and shift before combining the site total. Grade mix can change the blended margin even when each individual grade performs steadily. Distinguish genuine price changes from discounts, refunds, timing differences and invoicing corrections. Where stock valuation is provisional, mark the figure accordingly and refresh it when invoices arrive. The objective is a dependable decision signal, not false precision from incomplete data.
How should fuel margin connect to total site profit?
Build a price-change log that records the previous price, new price, effective time, commercial reason and expected contribution effect. Compare results over comparable trading periods, accounting for opening hours, availability and unusual traffic. A promotion that coincides with a delivery disruption cannot be judged fairly from a simple before-and-after volume comparison. Record those limitations so the next decision uses evidence rather than an attractive but misleading average.
Review supply terms beyond the headline rack differential. Delivery scheduling, minimum quantities, credit arrangements and contractual adjustments can change the effective acquisition cost. Confirm what the invoice includes before adding another allowance in the margin model. When evaluating a different supply arrangement, distinguish recurring improvements from temporary credits and consider working-capital implications. A larger delivery may improve freight economics while increasing inventory exposure and reducing available cash.
Finally, allocate responsibility for the next action rather than circulating the same report repeatedly. The pricing owner should explain selling-price changes, procurement should resolve invoice discrepancies, and operations should investigate stock and process exceptions. Finance should reconcile the resulting totals and challenge inconsistent definitions. This division of responsibility keeps the margin review commercially useful without asking a single site manager to resolve every issue alone.
Set a contribution plan alongside the operating budget and review actual results against both. Fuel may support convenience store traffic, but c-store sales are not automatically incremental profit. Use store gross profit after relevant costs, not store revenue, when assessing a fuel promotion. Keep labour and utilities visible so a successful volume campaign does not conceal longer opening hours or additional staffing requirements.
Make the daily review actionable: identify what changed, estimate its financial effect and agree the next decision. Then reconcile the daily picture to the monthly accounts so inventory valuation and late invoices are not forgotten. A daily performance review with Andrils can connect these controls to budgets, SOPs and plan-versus-actual reporting, giving managers a consistent view of contribution rather than a collection of disconnected averages.
Keep the agreed definitions in the report itself so a new manager can interpret the numbers without reconstructing last month's assumptions.