Petrol station valuation is the process of estimating what a buyer would pay for a defined fuel retail business on stated terms. The answer depends on sustainable cash generation, property rights, supply obligations and site liabilities, not simply annual fuel sales. Whether you call it a gas station, petrol station or forecourt, start by defining the transaction perimeter before discussing a multiple. A precise perimeter prevents buyers and sellers from comparing prices for fundamentally different assets.
What does a petrol station valuation actually include?
Separate the operating business from the property and from assets owned by suppliers or equipment providers. A freehold sale may include land and buildings; a leasehold transaction transfers only the rights permitted by the lease. Identify whether tanks, dispensers, canopy, payment systems and convenience store equipment belong to the seller. Confirm access rights and operating permissions rather than assuming that physical possession means unrestricted ownership.
State how fuel inventory, c-store stock, cash, debt and working capital will be treated. A headline price excluding stock is not directly comparable with one that includes stock at completion. Similarly, an enterprise value assumes a specified financing and working-capital basis. Document the assumptions in the valuation instruction and repeat them in the offer, so subsequent negotiations concern evidence rather than competing definitions.
How do you calculate sustainable station EBITDA?
EBITDA means earnings before interest, tax, depreciation and amortization. Rebuild it from reconciled trading records, not just a presentation prepared for sale. Connect fuel volumes to pump sales, deliveries, inventory movements and supplier invoices. Analyze convenience store gross profit separately from fuel contribution, then deduct the staffing, utilities, maintenance, insurance and occupancy costs needed to operate the site under the proposed ownership model.
Which adjustments should a buyer accept?
Normalize owner remuneration to the cost of replacing the work actually performed. Remove a genuinely nonrecurring expense only when supporting invoices and circumstances show it will not recur. Challenge proposed add-backs for deferred repairs, recurring professional fees or ordinary staff cover. If the seller owns the property but the buyer will lease it, introduce a defensible rent charge before applying a leasehold operating-business multiple.
Check monthly earnings across a period that captures seasonality and explain exceptional closures or changes in trading hours. A temporary increase in fuel margin is not automatically sustainable. Use daily reconciliation and performance analysis to understand which operating records support earnings quality. Distinguish improvements already achieved from buyer initiatives that still require investment, management effort or planning approval; the latter belong in a separate upside case.
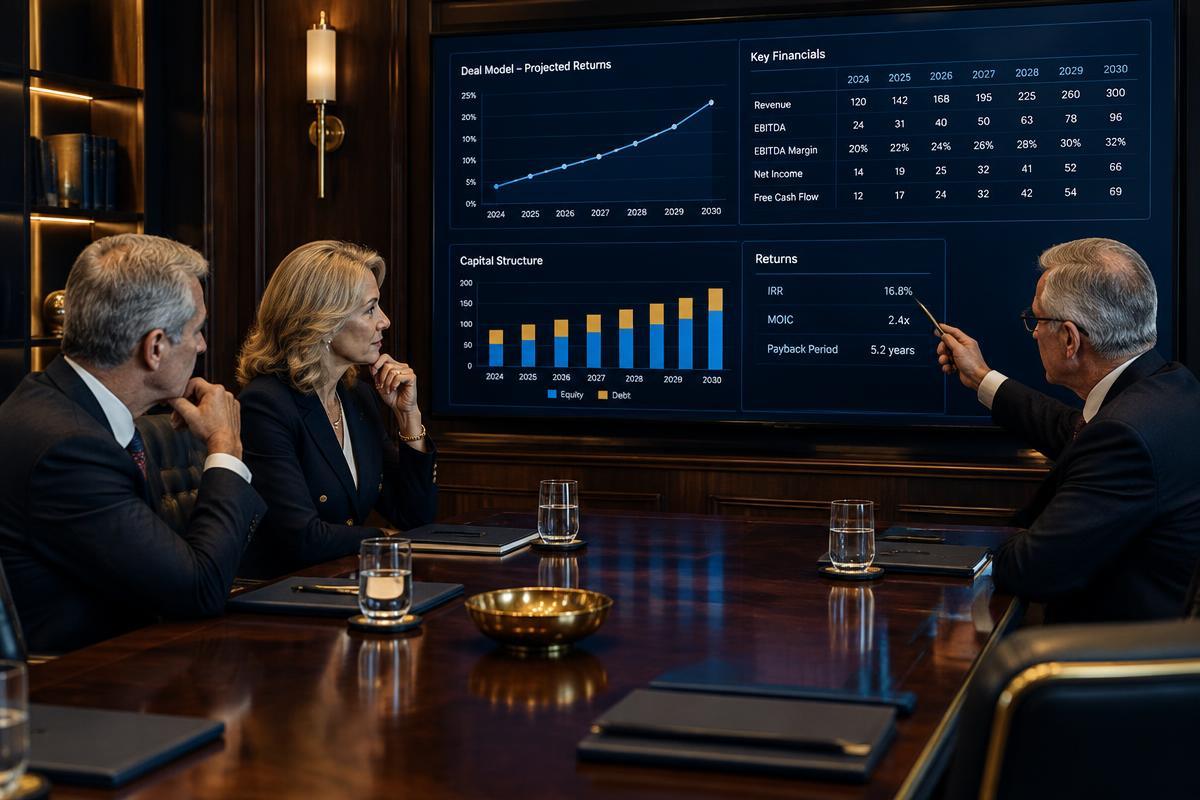
How does the EBITDA multiple formula work?
The multiple must match the property, lease, accounting and transaction perimeter. An illustrative multiple is not a market benchmark.
For an illustrative example, suppose reported annual EBITDA is $420,000. Add back a documented, nonrecurring legal expense of $30,000 and deduct $50,000 to replace underpaid owner management. Normalized EBITDA is therefore $400,000. Applying an illustrative 5.0 times multiple gives enterprise value of $2,000,000. This is arithmetic for a hypothetical transaction, not a statement about the multiple any particular station should command.
For the same illustrative example, assume $300,000 of debt, $50,000 of surplus cash and a $40,000 working-capital shortfall against an agreed completion target. Equity consideration would be $1,710,000 before transaction fees and seller taxes. The calculation is $2,000,000 minus $300,000 plus $50,000 minus $40,000. Check debt-like items separately, including unpaid capital expenditure and supplier balances whose treatment differs from ordinary trading creditors.
Define each item in the sale agreement and avoid counting the same liability in both debt and working capital.
Which valuation methods should you compare?
Use the earnings approach when maintainable operating profit can be demonstrated and the selected multiple is supported by genuinely comparable evidence. Asset-based valuation considers the value of identifiable assets less relevant liabilities, with specialist property and equipment input where needed. It can reveal whether an earnings case overlooks valuable property, but book value and replacement cost are not automatically realizable sale value.
Discounted cash flow, or DCF, estimates the present value of future cash flows after operating costs, taxes, working-capital movements and capital expenditure. It is useful when material changes in trading or investment timing make a single earnings year misleading. Model terminal value consistently with remaining lease rights and asset life. A spreadsheet cannot make uncertain assumptions reliable merely by projecting them further into the future.
The illustrative chart contains nine scenario estimates across three methods, not three independent pools of value. Investigate differences instead of averaging them mechanically. An asset estimate may imply an alternative use that is unavailable without consent; a DCF may assume growth unsupported by traffic or customer evidence. Align rent, property ownership, taxes and capital requirements first, then explain why one method deserves more weight for the actual transaction.
What makes a fuel station worth more or less?
A site with dependable earnings, transferable rights and clear maintenance records offers a different risk profile from one with unexplained losses or uncertain tenure. Review supply contract duration, exclusivity, pricing mechanisms, volume commitments, rebates and termination provisions. Attractive historical fuel margins can disappear if the buyer cannot retain the underlying supply terms. Check whether branding support carries repayment obligations or restricts future changes to the forecourt.
Environmental uncertainty needs qualified technical assessment and jurisdiction-specific legal advice. Tank age alone does not establish contamination or clean condition. Review testing, incident history, monitoring records and any remediation obligations. Avoid treating an indemnity as equivalent to eliminating the risk: enforceability, claim limits and the seller’s capacity to pay matter. Material uncertainty may require further investigation before an acceptable price or financing structure can be determined.
How should capital expenditure and EV charging affect value?
EBITDA excludes capital expenditure, so a station can look profitable while approaching a major cash outlay. Separate routine operating maintenance from replacement capital and discretionary expansion. Obtain condition reports and scoped estimates for tanks, dispensers, electrical systems and store equipment. Reflect cash requirements explicitly in a DCF or a transparent adjustment, avoiding duplication when the earnings multiple already incorporates a comparable level of asset condition.
Treat EV charging as a site-specific investment case rather than an automatic valuation premium. Test available power, connection obligations, parking turnover, customer dwell time and commercial rights. Include any partner revenue share and demand-related electricity charges where applicable. Preserve an evidenced base case without speculative charging income, then show a separate scenario with investment timing, operating assumptions and downside exposure that a buyer can interrogate.
How do you turn the valuation into an executable offer?
Stress-test the model before negotiating a narrow range. For an illustrative downside case, hold fuel volumes flat, remove an unconfirmed supplier rebate and bring forward identified replacement expenditure. Assess whether the business can still fund ordinary operations and required investment. Keep acquisition financing separate from operating value: a buyer's preferred debt structure does not establish what the underlying assets earn. Lenders may also require evidence or protections that differ from those negotiated between buyer and seller.
Comparable transactions require careful interpretation. Check when a deal completed, what was purchased, whether the price was publicly verified and how earnings were calculated. A multiple quoted without those details is not a reliable anchor. Portfolio benefits, exceptional property rights and buyer-specific synergies can make a comparison misleading. If robust evidence is unavailable, acknowledge that limitation and widen the scenario range instead of presenting a precise multiple as an observable fact. A valuation conclusion should explain uncertainty as clearly as it explains the central estimate.
Present a range with a clear base case, evidence requirements and a bridge to consideration. Explain which assumptions are confirmed, which require diligence and which depend on third-party consent. Compare an asset purchase and a share purchase with legal and tax advisers because liability transfer, permissions and completion mechanics can differ. Specify treatment of stock, employee obligations, lease deposits and supplier support rather than leaving these matters for completion day.
Use Andrils Deals advisory to connect valuation, diligence findings and deal structuring without confusing advisory work with legal, tax or environmental certification. For sellers, a well-organized evidence pack makes the earnings case easier to assess. For buyers, a disciplined walk-away position protects against paying for improvements twice: once through the purchase price and again through the capital and execution effort needed to deliver them.